What Accounting Professionals Should Ask Before a Client Buys, Renovates, or Holds Commercial Property
By Vernon Williams, Principal, Brighton Financial & Insurance Services
A commercial real estate decision involves more than purchase price, financing, tax treatment, and closing documents. Insurance is part of the transaction too, and a coverage gap can cost a client long after the deal closes.
A CPA advising real estate investors, developers, and business owners does not need to become an insurance specialist. The job is to recognize when a client's insurance program no longer matches the property's use, ownership, occupancy, construction plans, or transaction timeline, and to bring in an experienced insurance professional early.
One question covers most of it: does the client's insurance match what is happening with the property today and what is planned next?
Why Commercial Property Insurance Gaps Happen
Commercial property risks change quickly. A building moves from occupied to vacant, from operating to under renovation, or from one owner to another. Policies are underwritten on the facts given at binding, so when the facts change and nobody reviews the coverage, the policy may no longer fit the risk.
6 Commercial Property Insurance Gaps CPAs Should Watch For
1. The Client Acquires Property Without Confirming Coverage Before Closing
Clients focus on financing, due diligence, and the closing schedule, and insurance gets handled in the final days. That leaves little time to resolve underwriting questions, property condition issues, or lender requirements, and a lender will not fund without acceptable evidence of insurance.
CPA takeaway: Ask whether the insurance advisor has been involved before the closing date and whether coverage will be effective the moment ownership transfers.
2. The Property Will Be Vacant
Vacancy is the gap clients most often miss. Under the standard ISO commercial property form, a building is generally considered vacant when less than 31% of its square footage is rented or in use. Once it has been vacant for more than 60 consecutive days, the policy typically:
- Pays nothing for vandalism, theft, water damage, building glass breakage, or sprinkler leakage
- Reduces payment for any other covered loss by 15%
Carrier and surplus lines forms vary, and some are stricter. Vacant-building coverage and vacancy permit endorsements exist, but they have to be arranged before the loss.
CPA takeaway: Ask whether the property will be occupied, partially occupied, or vacant after acquisition, and whether the insurance advisor knows the actual occupancy plan.
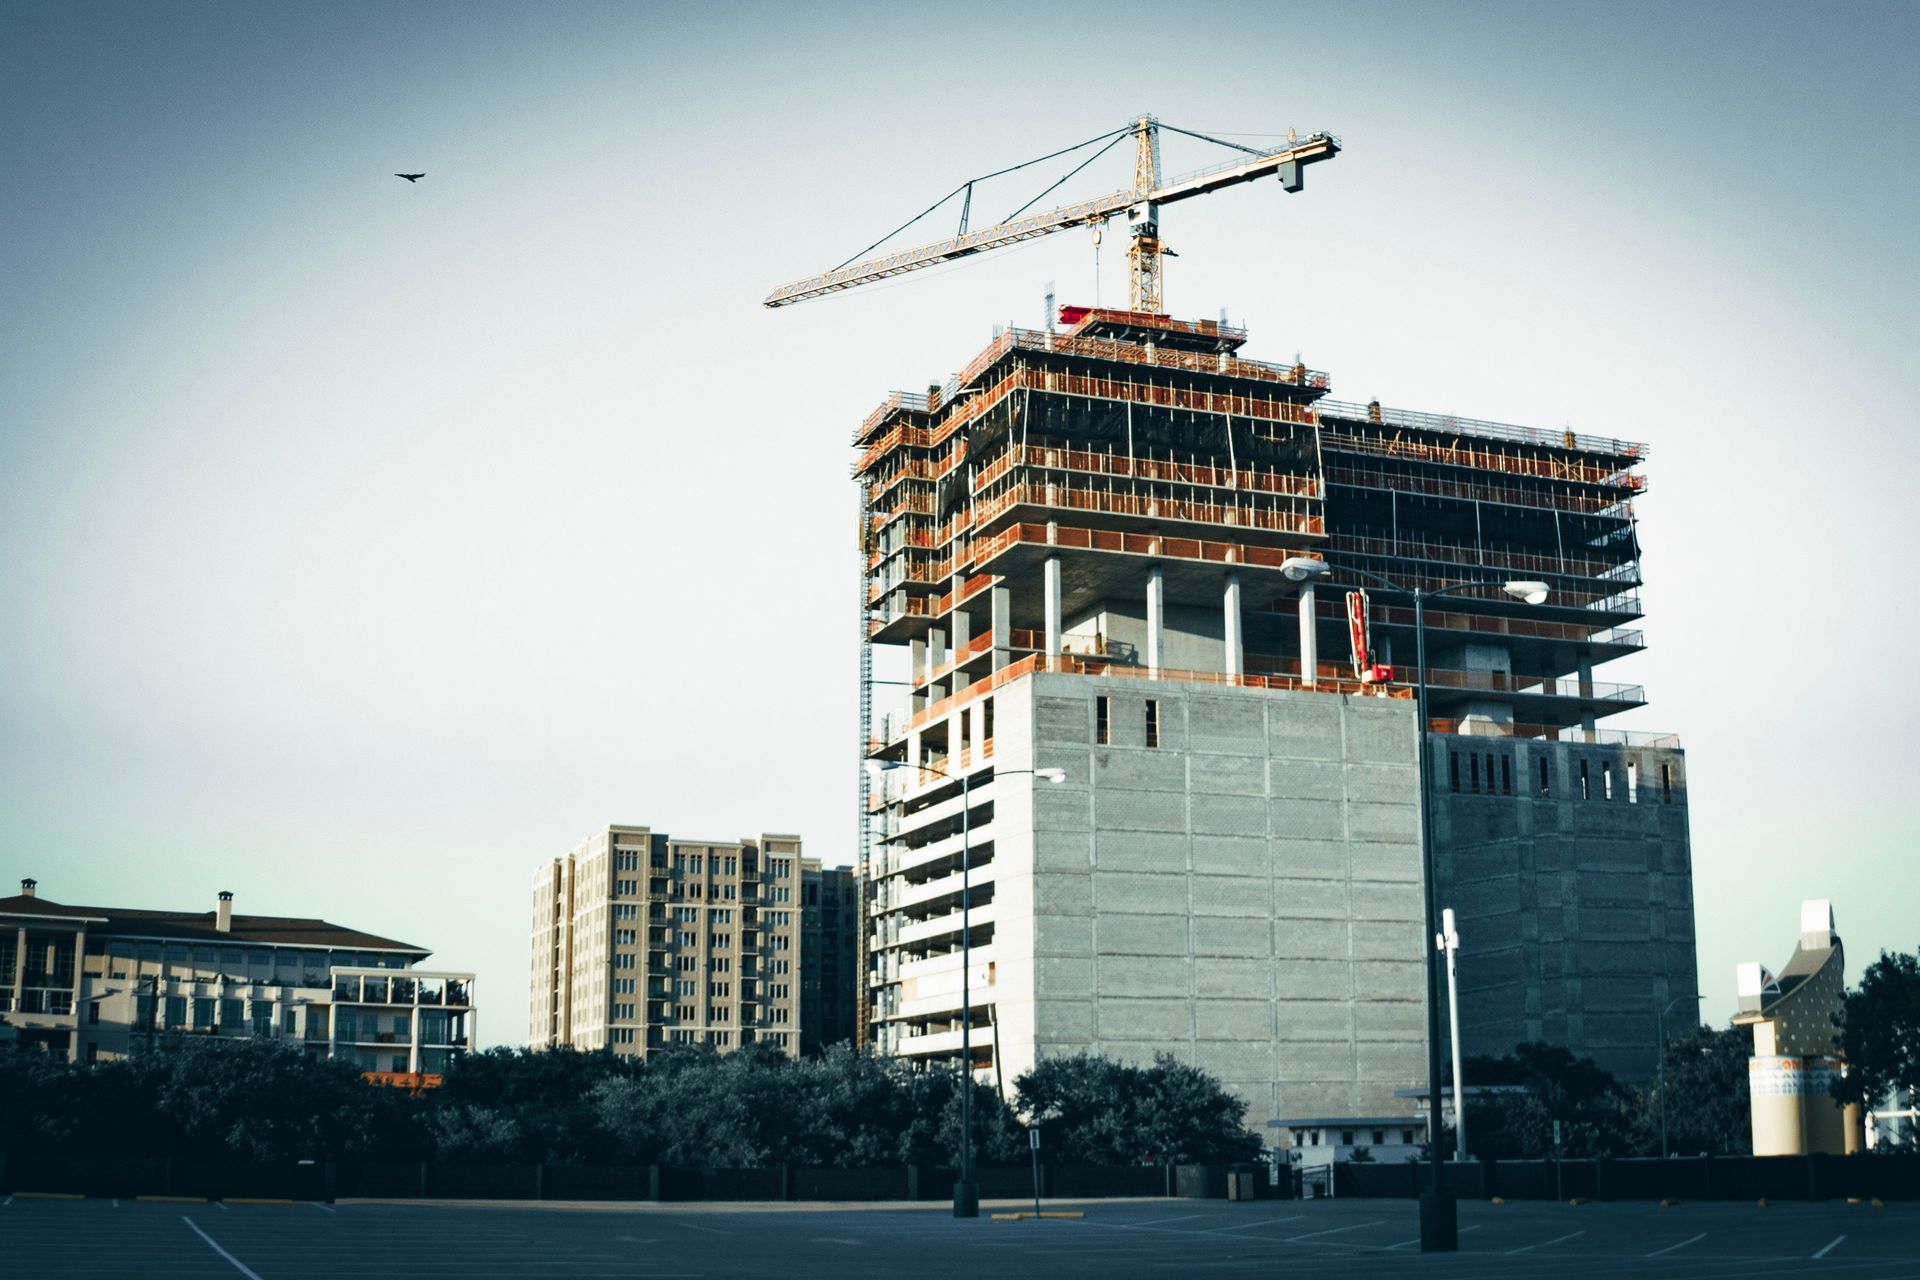
3. Renovation or Construction Is Planned
A client who buys an existing building to renovate or reposition it has changed the risk. A standard property policy is not designed for a building under construction, and builder's risk insurance or a renovation form may be needed instead of, or alongside, the existing coverage.
CPA takeaway: When a renovation or construction project comes up, recommend an insurance review before work begins.
4. The Property's Use Is Changing
Insurance should reflect how the property is actually used. A client may change tenants, convert part of the building, or move from an operating property to a hold-and-renovate strategy. Each of those can change the classification, the rate, and the carrier's willingness to write the risk.
CPA takeaway: Ask what the client intends to do with the property after acquisition. The planned use matters as much as the current one.
5. The Client Assumes the Seller's Policy Will Continue
It will not. A commercial property policy protects the named insured and cannot be assigned to a buyer without the carrier's written consent. The buyer needs its own program in place at closing.
CPA takeaway: Confirm that the buyer has arranged its own coverage and that the effective date matches the ownership transfer.
6. The Deal Involves Multiple Properties or a Hard Deadline
What looks like one insurance task can become several separate placements. Properties differ in condition, occupancy, location, and carrier appetite. A deadline compounds the problem: a 1031 exchange gives the client 45 days to identify replacement property and 180 days to close, and underwriting does not move faster because the clock is running.
CPA takeaway: In multi-property and deadline-driven transactions, start the insurance conversation as soon as the acquisition strategy is set.
The Section 263A Question: Are Construction-Period Premiums Deductible?
This one sits in the CPA's lane. For clients producing or substantially improving real property, the uniform capitalization rules treat insurance as an indirect cost (Treas. Reg. §1.263A-1(e)(3)(ii)). Premiums allocable to the construction activity, with builder's risk the clearest example, generally must be capitalized into the basis of the property instead of deducted currently. The main exception is the small business taxpayer exemption under §263A(i), which applies to taxpayers that meet the §448(c) gross receipts test.
The determination belongs to the CPA. The insurance advisor's part is documentation: separate premium figures for the construction period, clear policy dates, and an allocation the CPA can support.
What Should CPAs Ask Before a Client Acquires Commercial Property?
Property
- What type of commercial property is the client purchasing?
- Is it occupied, partially occupied, or vacant?
- Will it remain vacant after closing, and for how long?
- Are renovations, construction, or major improvements planned?
Transaction
- When does ownership transfer?
- Has the insurance advisor reviewed the transaction timeline?
- Is the client working under a 1031 exchange or another hard deadline?
Lender
- Does the lender have specific insurance requirements?
- Has the insurance advisor received them?
- Has the evidence of insurance been prepared and reviewed?
Coverage
- Does the insurance structure fit the property's occupancy and planned use?
- Are vacancy and renovation addressed?
- Are the lender's mortgagee interests reflected?
These questions are not meant to settle the correct policy or limits. They identify when the insurance conversation needs to happen.
Why Insurance Belongs in the CPA's Advisory Conversation
CPAs see a client's acquisition plans, financing, ownership structure, and capital improvements before almost anyone else does. That makes the CPA the natural early warning point when a property's insurance needs are about to change. The handoff can be simple: when a client is buying, renovating, changing occupancy, or acquiring several properties, an early introduction to an insurance professional catches gaps before they become claim or closing problems.
Frequently Asked Questions
Can a CPA determine whether a client's commercial property insurance is adequate?
No, and a CPA does not need to. The CPA's role is to notice changes in the property, ownership, occupancy, or plans and recommend an insurance review when they occur.
When should a client arrange commercial property insurance?
Well before closing, ideally as soon as the property is under contract. Early involvement gives the insurance advisor time to review the property, answer underwriting questions, and meet lender requirements.
Does a commercial property policy automatically cover a vacant building?
No. Under the standard form, a building vacant for more than 60 consecutive days loses coverage for several causes of loss and takes a 15% reduction on the rest. Occupancy status should be disclosed before coverage is bound.
What if the client plans to renovate after purchasing the property?
Tell the insurance advisor before work begins. Significant renovation usually calls for builder's risk or a renovation form, since a standard property policy is not built for construction.
Does the seller's insurance continue after the buyer takes ownership?
No. The seller's policy covers the seller. The buyer needs its own coverage effective at closing.
Why is early insurance involvement important for multi-property acquisitions?
Each property can require its own underwriting, and some may need different carriers. One closing date can mean several placements running in parallel, so lead time matters.
Key Takeaways for CPAs
Gaps develop when occupancy, use, ownership, or construction plans change without an insurance review.
- A building vacant more than 60 days can lose much of its coverage under the standard form.
- The seller's policy does not protect the buyer.
- The buyer's effective date should match the ownership transfer and satisfy the lender.
- Construction-period premiums may need to be capitalized under Section 263A.
- In multi-property and deadline-driven deals, start the insurance conversation early.
Related Reading
- What Happens When Builder's Risk Insurance Ends?
- Insurance and Commercial Real Estate Closings: A Pre-Closing Checklist for Attorneys
Why Work with BFIS?
Brighton Financial & Insurance Services (BFIS) works with commercial property owners, real estate investors, developers, contractors, and the CPAs and attorneys who advise them. Our specialties include:
- Commercial real estate insurance
- Builder's risk insurance
- Commercial property insurance
- General liability
- Workers' compensation
- Surplus lines placement
- Multi-state commercial insurance programs
With offices in San Ramon, California and Fort Lauderdale, Florida, and a principal licensed in 30 states, BFIS serves clients and referral partners across multiple markets.
Talk to a commercial insurance specialist: call (888) 412-7630, email vernon@thebfis.com, or
contact us online.

Get Started Today!
We'll Reply in 15 min or less within our business hours: 9:00 am to 5:00 pm, Monday-Friday
Contact Us
*Response time varies based on hours of operation